
Dubai Real Estate Market Report – May 2026
In May 2026, Dubai's real estate market demonstrated a combination of stabilizing transaction activity, diverging price trends, cautious land acquisitions, and continued strength in the rental sector. Residential sales moderated from previous highs, off-plan demand normalized, and ready-property prices remained resilient. Land market activity slowed as developers adopted a more disciplined approach to acquisitions, while rental demand remained robust, supporting steady rental growth.
Backed by ongoing economic initiatives, industrial development, and sustained inflows of global capital, Dubai's long-term real estate fundamentals remain strong. The current market adjustment is creating attractive opportunities for investors seeking quality assets.
1
Market Overview: Transactions Moderate While Core Assets Remain Resilient
In May 2026, Dubai's property market entered a phase of rational adjustment, with transaction activity slowing compared to previous months. Price performance varied significantly across asset classes and locations.
While residential and land market activity softened, premium properties and prime locations continued to demonstrate resilience. The rental market remained particularly strong, with rents reaching new cyclical highs.
Supported by Dubai's growing economy, expanding financial sector, and continued business activity, the market is transitioning toward a more sustainable pace of growth while maintaining solid long-term fundamentals.
2
Macro Environment: Strong Fundamentals Continue to Support Growth
Several major developments across the UAE during May further strengthened the foundations of the real estate market.
AED 1.5 Billion Economic Stimulus Package
Dubai launched a AED 1.5 billion economic incentive program comprising 33 initiatives to be implemented over the next 3–12 months. The program covers tourism, trade, education, aviation, and other key sectors, aiming to reduce business costs and attract additional talent and investment.
UAE Leads in Technology Adoption
The UAE achieved a global-leading AI adoption rate of 70.1%. Meanwhile, MENA Blockchain Week was hosted in Dubai, reinforcing the city's position as a hub for blockchain technology, artificial intelligence, digital payments, and the broader digital economy.
Continued Growth in Financial Services
The Dubai International Financial Centre (DIFC) reported significant growth in company registrations, financial licenses, and foundations during the first quarter of 2026, further strengthening its role as the region's leading financial hub.
At the same time, major global institutions such as Morgan Stanley and Man Group expanded their presence in Abu Dhabi, highlighting accelerating capital inflows into the UAE.
Landmark Luxury Land Transaction
A prime beachfront plot on Naïa Island was sold for AED 377 million, demonstrating continued confidence among global high-net-worth investors in Dubai's scarce waterfront assets.
Positive Momentum Across the UAE
Abu Dhabi's residential market also recorded strong performance, with transaction volumes rising 119% year-on-year during the first quarter, accompanied by increases in both property prices and rental rates.
3
Residential Sales Slow as Apartment and Villa Markets Diverge
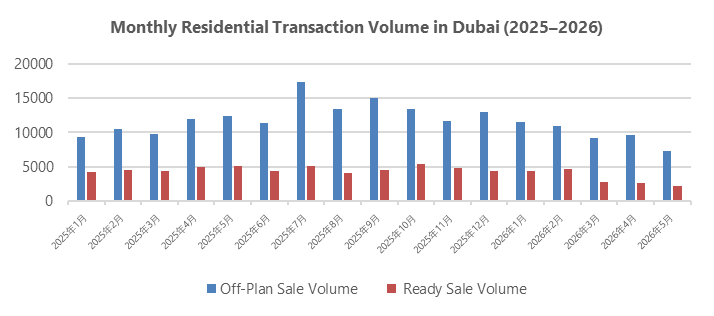
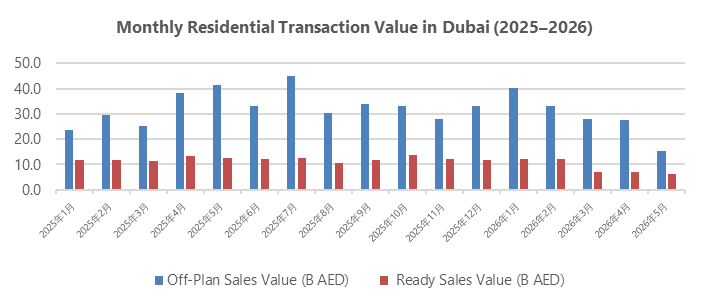
Dubai recorded 9,536 residential transactions in May, with a total transaction value of approximately AED 21.93 billion.
Off-Plan Market
Off-plan residential transactions reached 7,255 units, representing a 41.5% year-on-year decline. Average prices stood at AED 2,028 per square foot, down 10% month-on-month.
Ready Property Market
Ready-property transactions totaled 2,281 units, down 55.3% year-on-year. However, average prices increased by 10.1% month-on-month to AED 2,029 per square foot.
The divergence reflects a market increasingly segmented between investor-driven off-plan purchases and end-user demand supporting the ready-property sector.
Top 10 Areas by Transaction Volume
Off-Plan Apartments
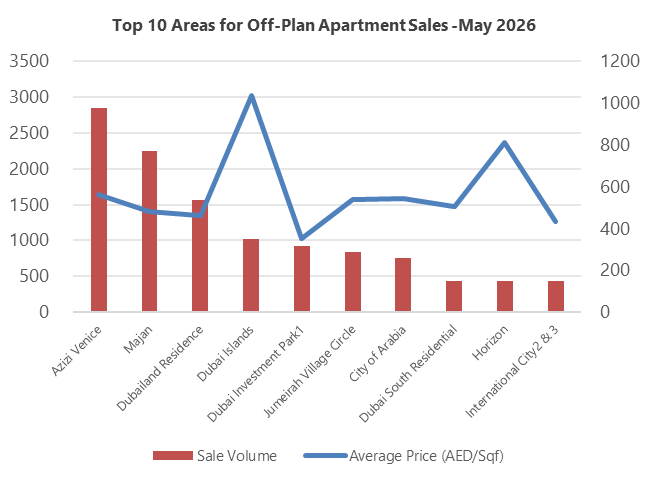
Off-plan apartment transactions reached 6,623 units, with average prices of AED 2,100 per square foot.
Communities such as Azizi Venice, Majan, and Dubailand Residence Complex generated significant transaction volumes due to their affordability and strong end-user appeal. Meanwhile, Dubai Islands continued to command the highest pricing and transaction values, reflecting strong demand for premium waterfront developments.
Ready Apartments
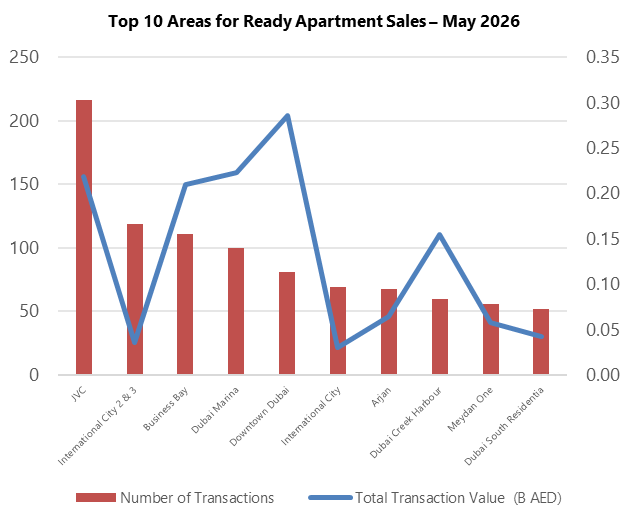
Ready apartment transactions totaled 1,865 units, with average prices reaching AED 1,801 per square foot.
Jumeirah Village Circle (JVC) remained Dubai's most active ready-property market by transaction volume, while established prime districts such as Downtown Dubai, Dubai Marina, and Business Bay continued to dominate transaction value rankings thanks to their premium pricing and strong occupier demand.
Off-Plan Villas
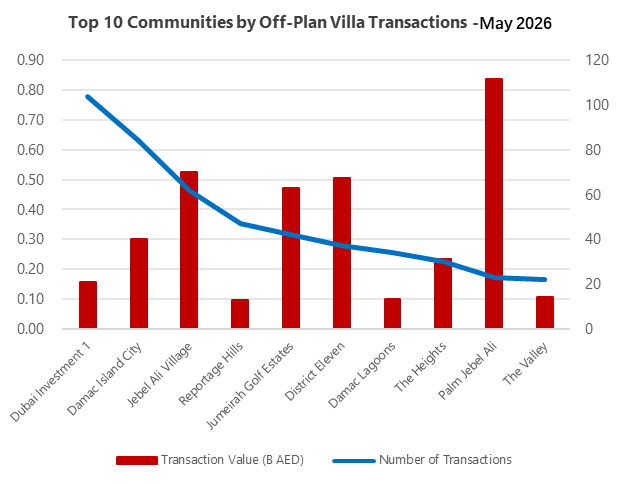
Off-plan villa sales totaled 632 units.
Dubai Investment Park and DAMAC Islands generated the highest transaction volumes among mid-market master-planned communities.
Palm Jebel Ali recorded fewer transactions but achieved the highest average prices and transaction values, highlighting the enduring appeal of ultra-luxury waterfront villas.
Ready Villas
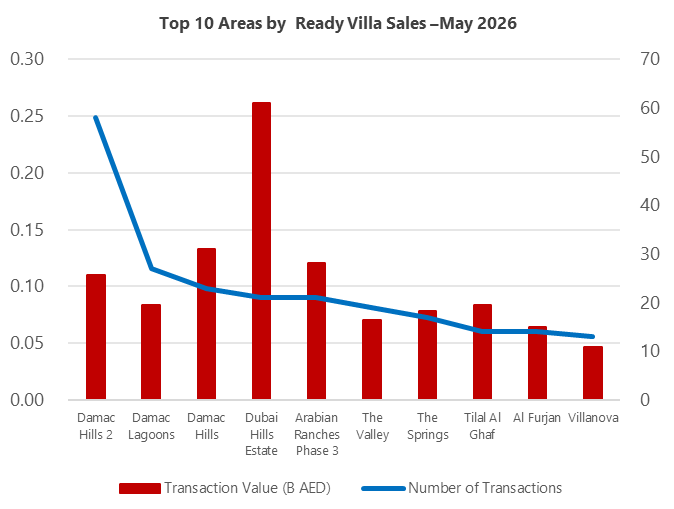
Ready villa transactions reached 416 units, while average prices rose sharply by 21.6% month-on-month to AED 2,348 per square foot.
Communities such as DAMAC Hills 2 remained popular among family buyers, while premium districts including Dubai Hills Estate continued to record strong price growth, supported by sustained demand from affluent end-users.
Top 10 Developers by Transaction Volume
Off-Plan Apartments
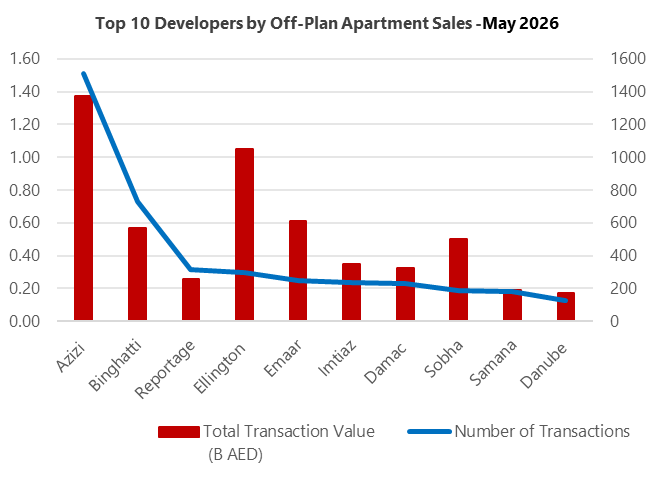
In terms of transaction volume, Azizi Developments led the market by a significant margin with 1,511 units sold, driven by its strong portfolio of compact, competitively priced properties that continue to attract broad buyer demand. Binghatti and Reportage Properties followed closely behind, reflecting the sustained popularity of mid-market residential projects among end-users and investors alike.
In terms of transaction value and average selling price, premium developers such as Ellington Properties, Emaar Properties, and Sobha Realty delivered strong performances. Their high-quality, lifestyle-oriented developments continued to command premium pricing and set the benchmark for Dubai's upper-end residential market.
Off-Plan Villas
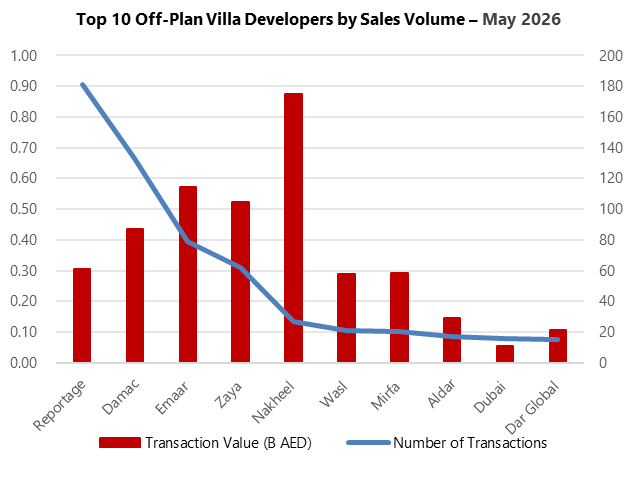
For transaction volume, Reportage Properties and DAMAC Properties led the market, supported by large-scale master-planned communities targeting the mid-market villa segment.
In terms of transaction value, Nakheel stood out as the clear leader, driven by its portfolio of ultra-luxury waterfront villa developments. With some of the highest average transaction values in the market, Nakheel's projects continue to attract strong interest from high-net-worth individuals seeking exclusive beachfront residences and long-term wealth preservation assets.
4
Land Market Slows as Developers Adopt a More Disciplined Approach
Dubai's land market continued its adjustment phase during May.
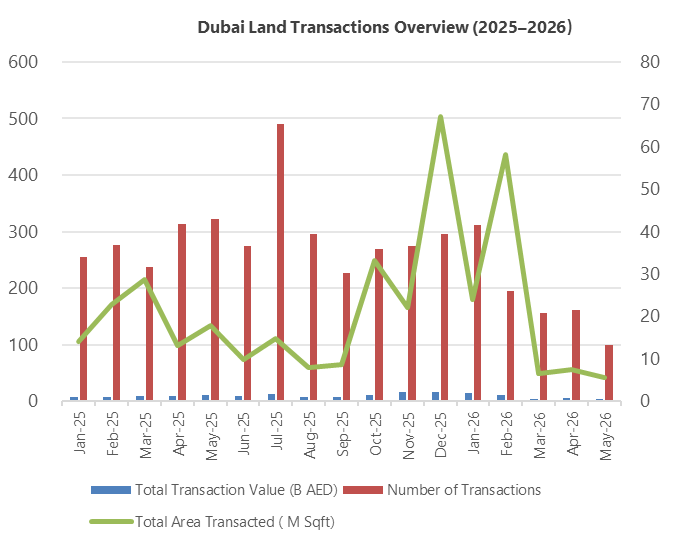
Total land transaction value reached AED 3.62 billion, down approximately 34% month-on-month. Transaction volume fell to 100 plots, representing a decline of roughly 38%, while total transacted land area decreased by more than 60% compared to both the previous month and the previous year.
Developers are becoming increasingly selective in their acquisition strategies, focusing on high-quality opportunities with clear long-term development potential.
Industrial and large-scale development sites accounted for a significant share of transactions, while premium waterfront locations including Palm Jumeirah, Pearl Jumeirah, and Al Mamzar continued to maintain strong land values due to their scarcity and desirability.
Industry sentiment remains positive toward approved development plots and mature residential locations, particularly within established waterfront communities.
5
Rental Market Remains a Key Source of Strength
Dubai's rental market continued to outperform, recording steady demand and rising rental rates despite a slight moderation in transaction activity.
Apartments
Rental Market: Rising Rents Continue to Support Strong Investment Returns
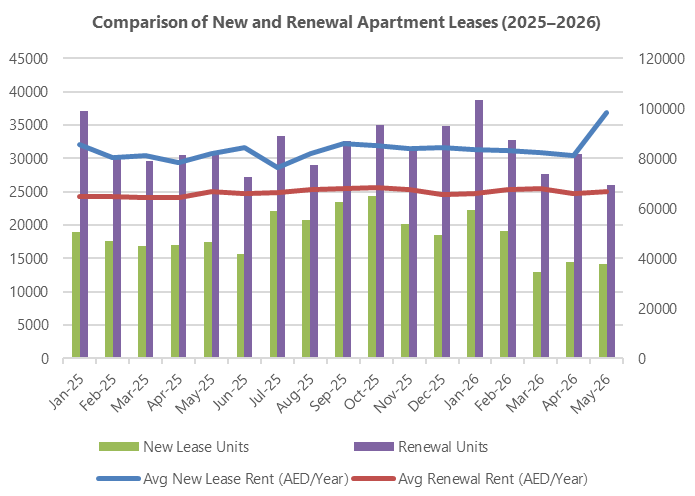
Dubai's rental market continued to demonstrate independent strength in May. While overall leasing activity moderated slightly, rental rates increased across both apartments and villas, driving higher rental yields and reinforcing the market's underlying resilience. Renewal demand remained stable, reflecting strong tenant retention and sustained confidence in the city's residential sector.
For apartments, the average annual rent for newly signed leases reached AED 98,370, while renewal leases averaged AED 66,947. A total of 14,147 new apartment leases and 26,038 lease renewals were recorded during the month.
In the villa segment, the average annual rent for newly signed leases climbed to AED 272,900, while renewal leases averaged AED 199,700. The market recorded 1,996 new villa leases and 2,911 renewals.
Overall, the rental market continues to exhibit a clear trend of strong growth in new lease rates alongside relatively stable renewal rents. Existing tenants remain committed to their current residences, while new entrants to the market face increasingly higher rental costs. This dynamic is supporting steady rental income growth and further strengthening the investment case for income-generating residential assets across Dubai.
Top 15 Areas by Rental Transactions
New Apartment Lease Transactions
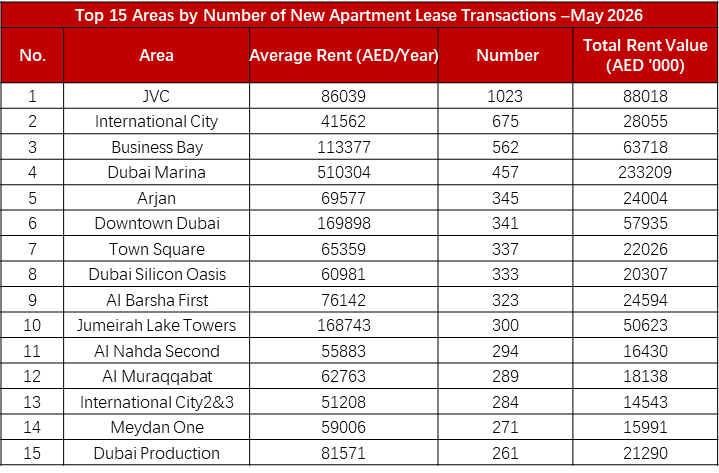
Mid-market communities such as Jumeirah Village Circle (JVC), International City, and Arjan continued to lead Dubai's apartment rental market by transaction volume, supported by their affordability, established infrastructure, and large tenant populations. These communities remain key destinations for residents seeking value-driven housing options and continue to generate strong leasing activity.
Meanwhile, prime districts including Business Bay, Dubai Marina, and Downtown Dubai maintained some of the highest rental rates in the city. Strong demand from professionals, executives, and international residents has continued to push rental values upward, further raising the entry threshold for Dubai's premium rental market and reinforcing the long-term appeal of these established core locations.
Apartment Lease Renewals
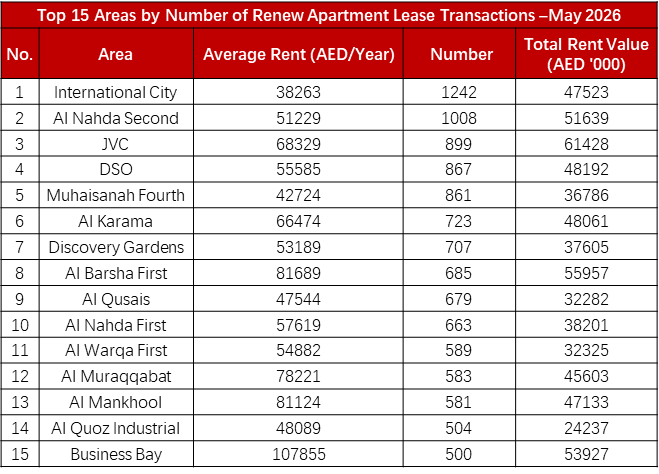
Communities such as International City, Al Nahda Second, Jumeirah Village Circle (JVC), and Dubai Silicon Oasis continued to rank among the leading areas for apartment lease renewals. Supported by mature infrastructure, established amenities, and relatively affordable rental rates, these communities have maintained strong tenant loyalty and high renewal activity.
The consistently high volume of lease renewals highlights the stability of Dubai's end-user rental market, with many residents choosing to remain in well-established neighborhoods that offer a balance of affordability, convenience, and quality of life. This trend underscores the strength of the city's mid-market rental segment and provides a solid foundation for sustained rental demand.
New Villa Lease Transactions
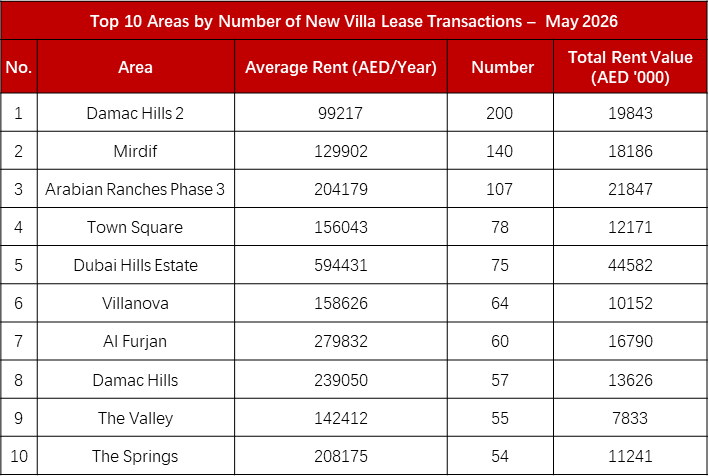
Family-oriented communities such as DAMAC Hills 2, Mirdif, and Arabian Ranches Phase 3 continued to capture the majority of new villa leasing demand, driven by their spacious layouts, community-focused environments, and attractive value proposition for families seeking long-term accommodation.
At the premium end of the market, Dubai Hills Estate maintained a clear lead in rental pricing, with luxury villas commanding some of the highest rents in Dubai. Demand from high-net-worth tenants remained resilient, reflecting the enduring appeal of well-established, master-planned communities that offer premium amenities, green spaces, and a superior lifestyle experience.
Villa Lease Renewals
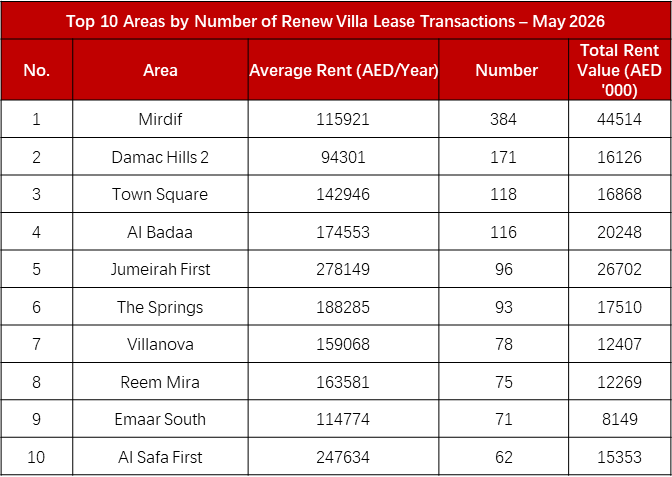
Mirdif continued to lead the villa lease renewal market by a significant margin, demonstrating exceptionally strong tenant retention and long-term residential appeal. Established family-oriented communities such as DAMAC Hills 2 and Town Square also recorded high levels of renewal activity, reflecting the stability of demand within these well-developed neighborhoods.
The strong renewal performance across these communities suggests that family tenants increasingly prefer to remain in areas that offer comprehensive amenities, quality schools, recreational facilities, and a well-established community environment. This trend highlights the growing importance of lifestyle and convenience in driving long-term residential commitment and reinforces the resilience of Dubai's family housing market.
6
Market Outlook: Short-Term Adjustment Creates Long-Term Opportunities
Compared with the gradual recovery observed in April, Dubai's real estate market entered a more measured and rational phase in May. The moderation in transaction activity reflects a return to a healthier and more sustainable pace of growth rather than any weakening of market fundamentals.
Property inventory remains sufficient across key segments, while ongoing government initiatives, economic diversification efforts, and continued inflows of international capital continue to support long-term market confidence. Prime locations, luxury properties, and rental-focused assets have consistently demonstrated strong resilience, maintaining their ability to generate stable returns even during periods of market adjustment.
The current environment also offers buyers and investors greater flexibility in negotiations, creating an attractive window to secure high-quality assets at favorable terms. End-users seeking a primary residence may benefit from focusing on completed properties within well-established communities. Investors targeting stable income can look toward highly liquid rental assets, supported by rising rents and strong tenant demand. For those pursuing long-term wealth preservation and capital appreciation, premium apartments and villas in central and waterfront districts remain among the most compelling opportunities in Dubai's real estate market.
【END】