
Dubai Real Estate Market Report – April 2026
Introduction
Dubai's real estate market in April 2026 continued to demonstrate resilience, with the first four months of the year characterized by moderated transaction volumes, stable pricing, improving market structure, and sustained investor confidence.
Off-plan properties continued to dominate sales activity, while the ready property segment showed signs of stabilization. Land transactions rebounded from recent lows, rental performance remained firm, and supportive policy developments—including visa rule enhancements and the approval of the Dubai Metro Gold Line—further strengthened the emirate's long-term investment appeal.
As Dubai transitions from short-term market fluctuations toward a more mature and sustainable growth phase, its value proposition as a global asset allocation destination continues to strengthen.
1. Market Overview: Stability Reinforced by Strong Fundamentals
In April 2026, Dubai's property market displayed signs of recovery following a temporary slowdown, while maintaining stable prices and healthy market fundamentals.
Although transaction volumes experienced a degree of adjustment, both property prices and rental values remained at elevated levels. Supported by investor-friendly policies and a balanced supply-demand environment, Dubai continues to stand out as one of the world's most attractive real estate investment destinations.
2. Macroeconomic Environment: Policy Support Strengthens Long-Term Outlook
Several significant developments during April further reinforced the foundations of Dubai's property market.
Property Visa Requirements Eased
The UAE expanded accessibility to its 2-Year Property Investor Visa. Sole property owners are no longer subject to a minimum property value requirement, while joint owners may qualify provided each individual share is valued at AED 400,000 or above.
The policy is expected to lower entry barriers for international investors and support continued population growth.
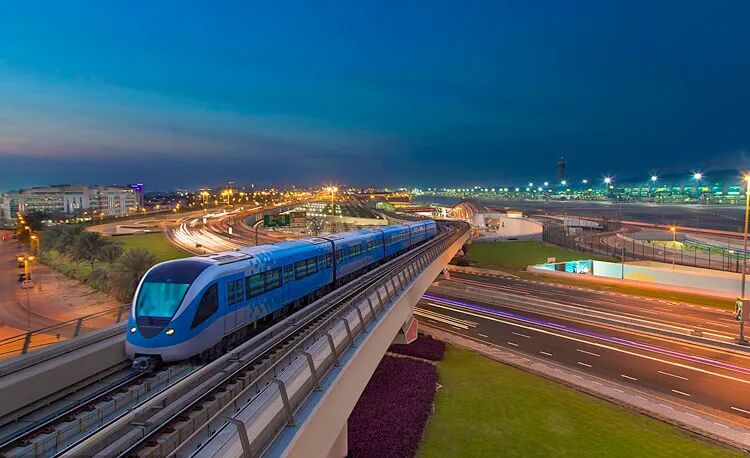
Dubai Metro Gold Line Approved
Dubai approved the development of the Metro Gold Line, a major infrastructure project valued at AED 34 billion.
The 42-kilometer route will connect 15 key districts and serve approximately 1.5 million residents. Properties located along the corridor are expected to benefit from enhanced connectivity and potential value appreciation.
Economic and Business Growth Remains Strong
The UAE continues to rank among the world's leading destinations for entrepreneurship and innovation. The country is strengthening its position as a global artificial intelligence hub, while office vacancy rates are projected to decline to just 0.7%.
Continued inflows of businesses, talent, and capital provide a strong foundation for sustained housing demand.
3. Residential Sales Market: Off-Plan Dominates While Apartments and Villas Diverge
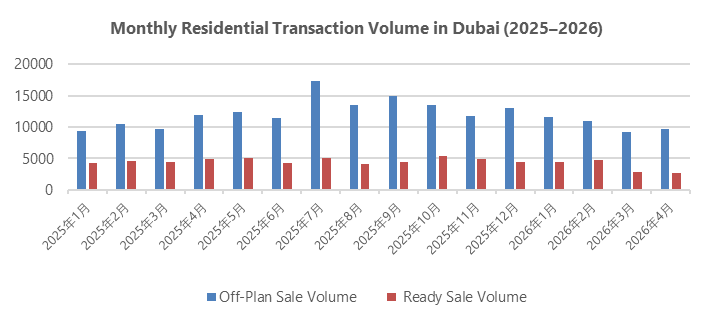
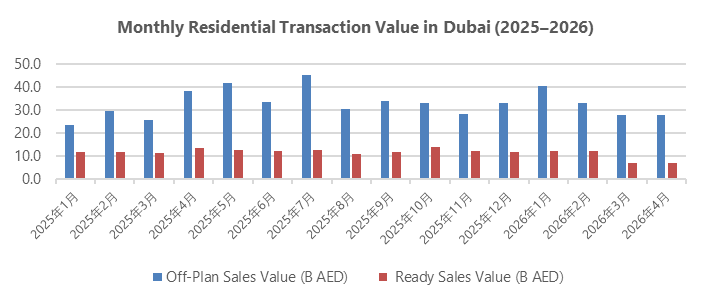
Dubai recorded approximately 12,385 residential transactions in April, generating a total transaction value of approximately AED 34.7 billion.
Off-plan properties accounted for 9,693 transactions, representing nearly 78% of total residential sales activity. The average off-plan transaction price reached AED 2,253 per square foot, reflecting a 7.1% month-on-month increase.
Ready property transactions totaled 2,692 units, declining both month-on-month and year-on-year. However, the average price remained relatively stable at AED 1,842 per square foot, indicating continued confidence among buyers.
Off-Plan Apartments
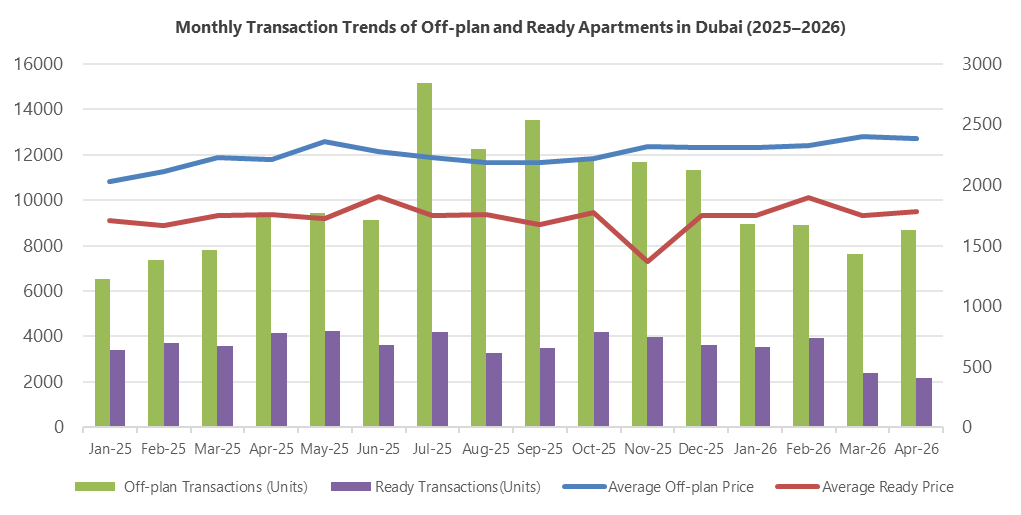
The off-plan apartment market recorded 8,685 transactions during April, approximately 14% higher than March.
Average prices reached AED 2,385 per square foot, representing an annual increase of approximately 8%.
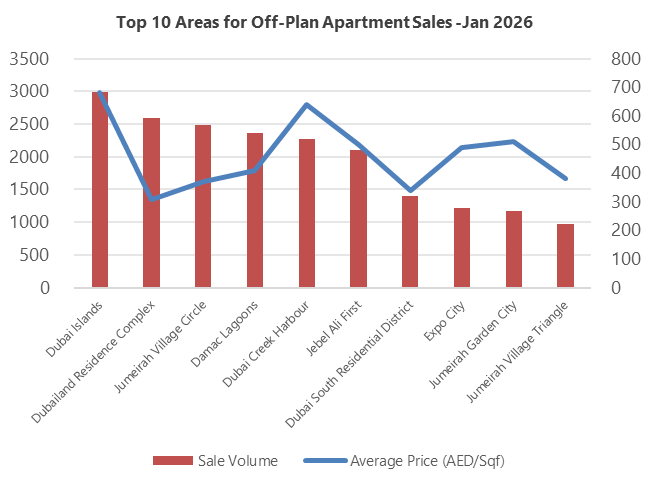
Volume-driven communities such as Dubailand Residence Complex, JVC, and Damac Lagoons contributed significant transaction activity, while premium destinations including Dubai Islands, Dubai Creek Harbour, and Expo City attracted substantial investment capital.
This reflects a healthy and diversified market structure across multiple price segments.
Ready Apartments
Ready apartment transactions totaled 2,180 units, representing a 47.5% year-on-year decline.
Average prices increased slightly to AED 1,781 per square foot compared with the previous month.
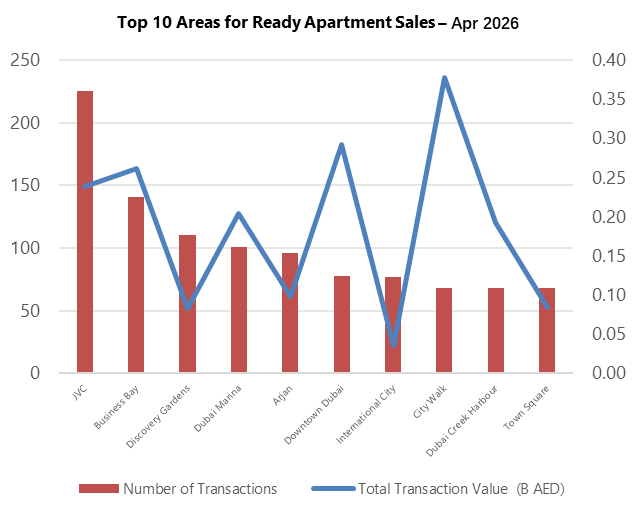
Established communities continued to lead activity, with JVC recording the highest transaction volume. Premium districts such as Business Bay, Dubai Marina, and Downtown Dubai maintained strong transaction values due to their higher price points and enduring demand.
Off-Plan Villas
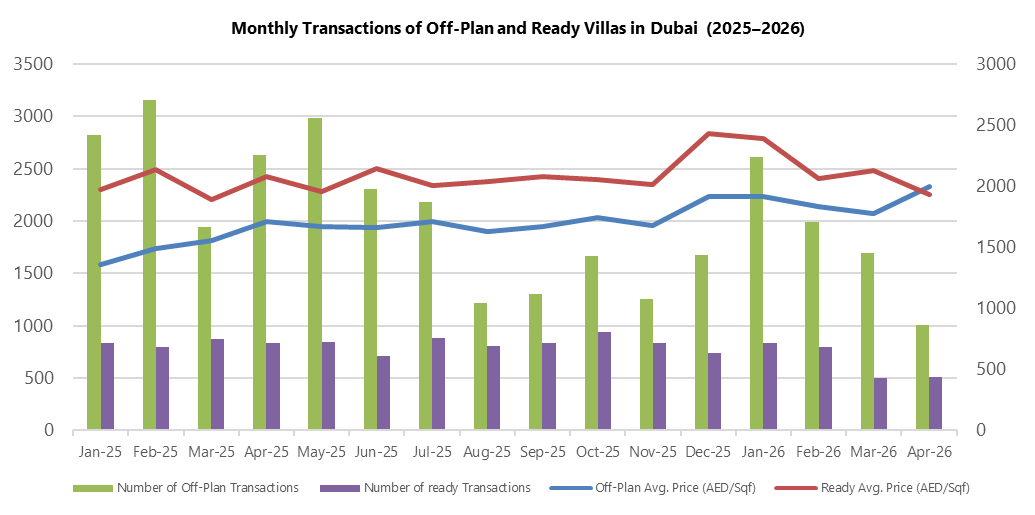
The off-plan villa market recorded 1,008 transactions, down 61.7% year-on-year, while average prices rose 12.6% month-on-month to AED 1,995 per square foot.
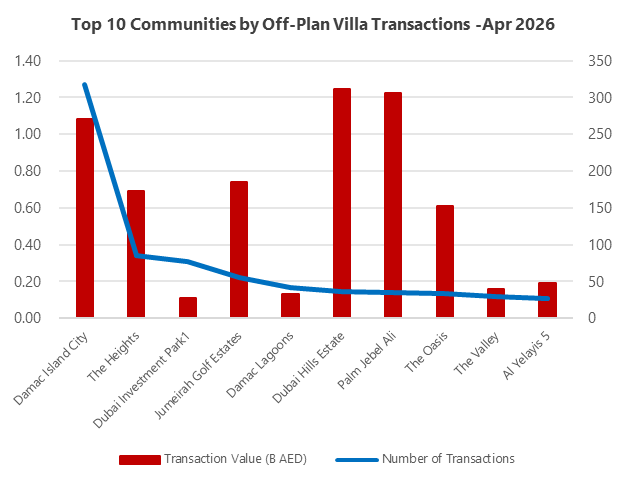
Large-scale master developments remained the key market drivers. Damac Island City led transaction volumes, while Dubai Hills Estate and Palm Jebel Ali ranked among the highest in transaction value.
Luxury communities such as The Oasis and Jumeirah Golf Estates continued to command premium pricing.
Ready Villas
Ready villa transactions reached 512 units, a 38.5% year-on-year decrease.
Average prices declined 9.1% month-on-month to AED 1,931 per square foot.
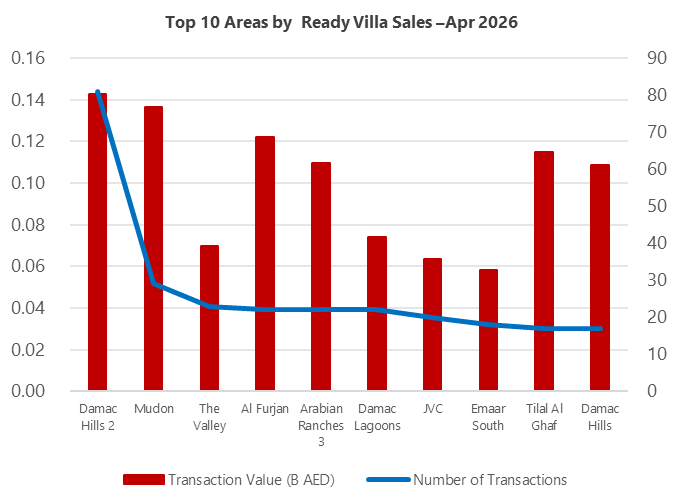
Established villa communities including Damac Hills 2, Mudon, Al Furjan, and Tilal Al Ghaf continued to demonstrate strong liquidity and resilient pricing fundamentals.
Top Performing Developers
Off-Plan Apartments
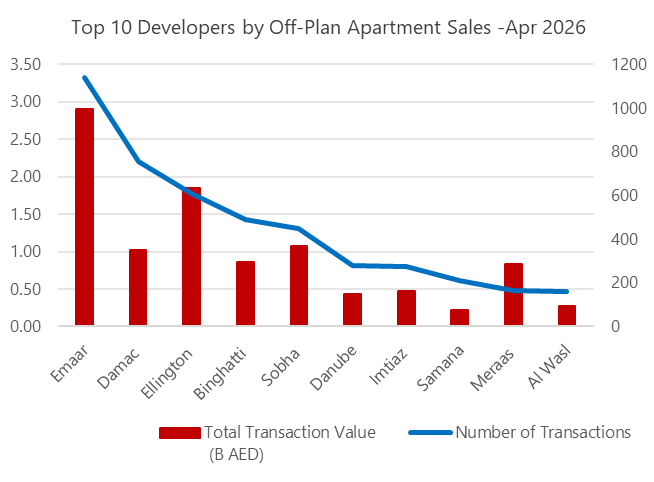
By transaction volume, Emaar ranked first with 1,139 sales, reflecting strong brand recognition and product absorption capability.
By transaction value, Emaar also led the market with AED 2.9 billion in sales. Premium developers such as Ellington and Sobha continued to perform strongly, while Meraas maintained its position in the luxury segment.
Off-Plan Villas
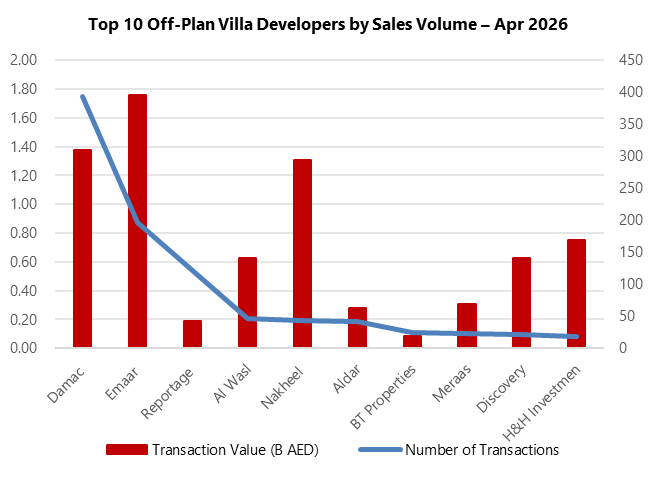
Damac led villa transaction volume with 393 sales, supported by its large-scale master-planned communities.
By transaction value, Emaar ranked first with AED 1.76 billion. Nakheel and H&H Investment achieved some of the highest average transaction values, reflecting the premium nature and scarcity of their villa offerings.
4. Land Market: Recovery Underway While Prime Locations Support Pricing
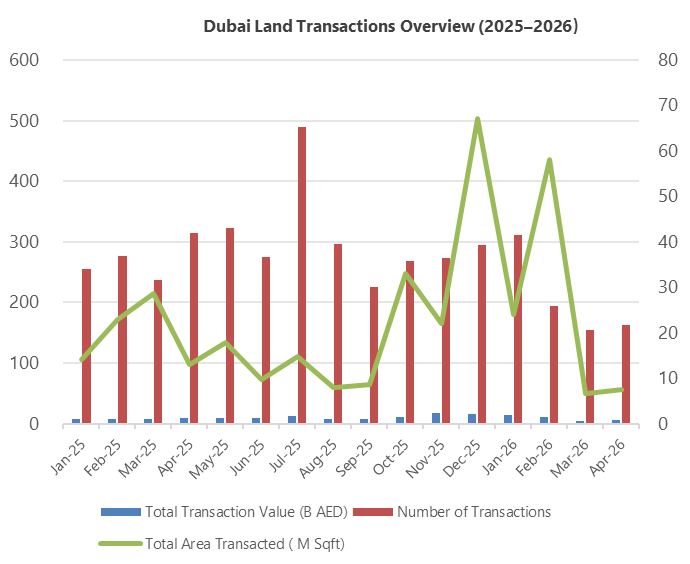
Dubai's land market showed signs of recovery from March's lower transaction levels.
April recorded 162 land transactions with a total value of approximately AED 5.52 billion, representing a 35% month-on-month increase.
Market activity was concentrated in emerging and industrial districts such as Jebel Ali Hills, Meydan One, and Nad Al Hamar, which contributed the majority of transaction volumes.
Meanwhile, premium locations including Palm Jebel Ali, Umm Suqeim First, Al Jadaf, and Business Bay accounted for a significant share of total transaction value, highlighting the continued scarcity and attractiveness of prime development land.
Developers remain selective and disciplined in land acquisitions, focusing on high-quality opportunities.
5. Rental Market: Stable Activity and Strong Renewal Demand
Dubai's rental market remained healthy throughout April, with occupancy rates and tenant retention levels continuing to perform strongly.
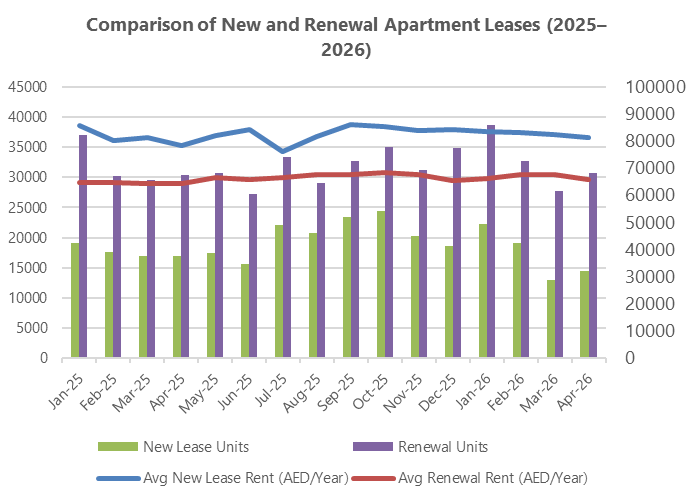
The average annual rent for newly signed apartment leases reached AED 81,216, while renewal contracts averaged AED 65,860.
A total of 14,413 new leases and 30,735 renewals were recorded, demonstrating that lease renewals remain the dominant source of rental activity.
Apartment Rental Highlights
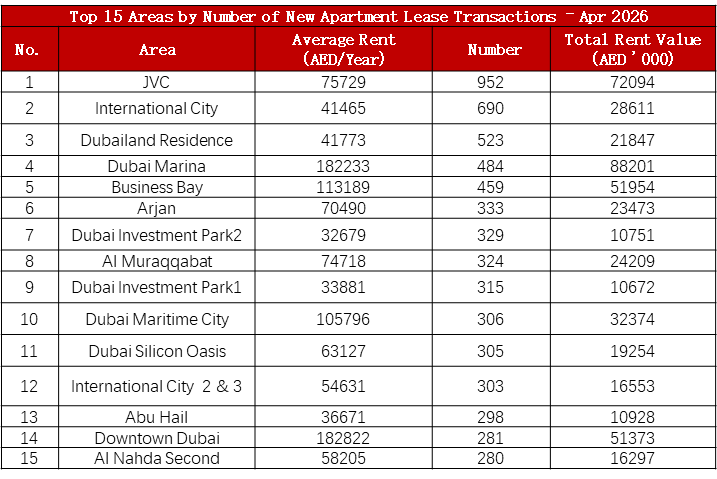
JVC, International City, and Dubailand Residence Complex recorded the highest volumes of newly signed apartment leases.
Dubai Marina and Downtown Dubai continued to achieve some of the highest average rental rates in the city, reinforcing their premium positioning.
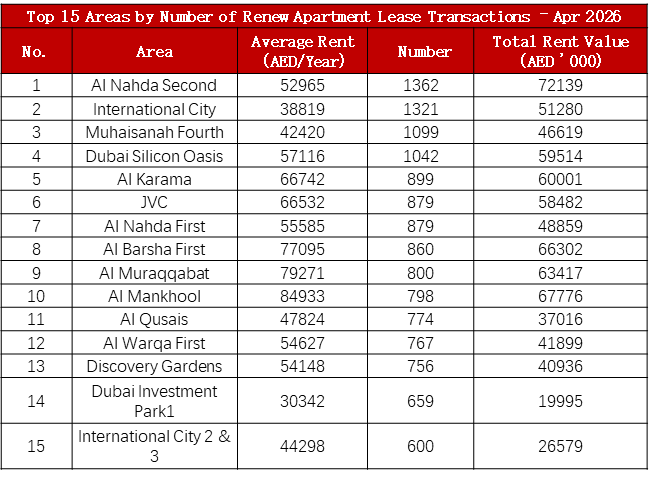
For lease renewals, mature residential districts such as Al Nahda Second, International City, and Muhaisnah Fourth remained among the most active areas, reflecting strong tenant retention and value-driven demand.
Villa Rental Highlights
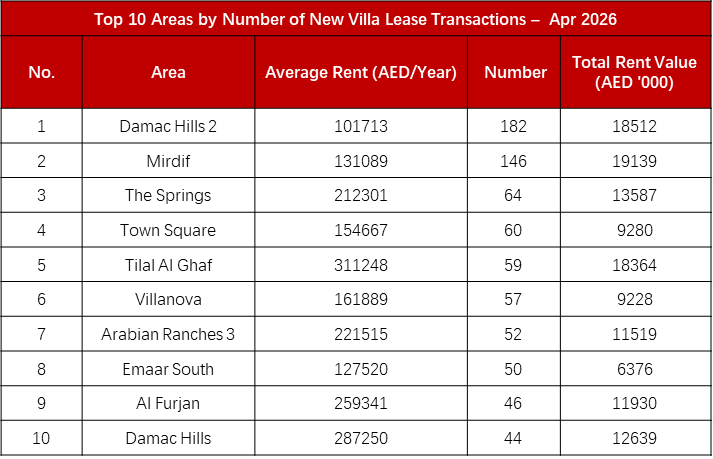
Damac Hills 2 and Mirdif led new villa lease transactions, supported by affordability and established community infrastructure.
Premium villa communities such as Tilal Al Ghaf and Damac Hills continued to achieve strong rental performance.
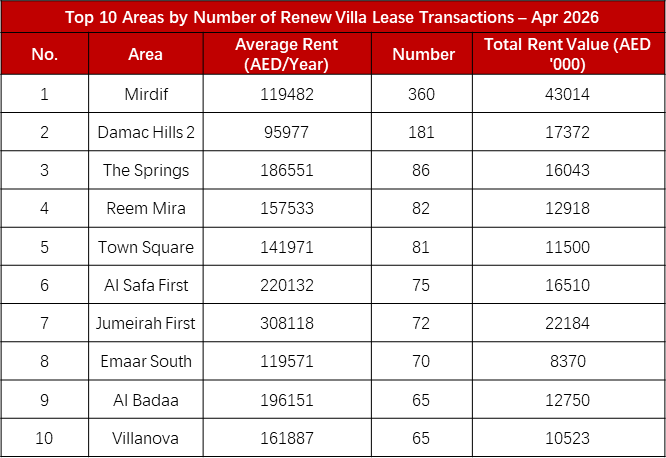
For renewals, Mirdif remained the most active villa rental district, while Jumeirah First and Al Safa First maintained some of the highest average rental levels in the market.
6. Market Outlook: Short-Term Fluctuations, Long-Term Opportunities
April's market data reinforces a consistent theme: the long-term fundamentals supporting Dubai's real estate sector remain firmly intact.
Government policy support, abundant investment opportunities, ongoing infrastructure development, and continued international capital inflows continue to underpin market growth.
While short-term fluctuations are natural in any maturing market, Dubai's core assets continue to demonstrate exceptional resilience.
For investors seeking long-term international diversification, the current environment presents a compelling opportunity to secure high-quality assets in strategic locations and participate in one of the world's most dynamic real estate markets.
[ END ]